FREE NEWSLETTER

It’s rare that we talk honestly about how much money we have—and we’re poorer for it.
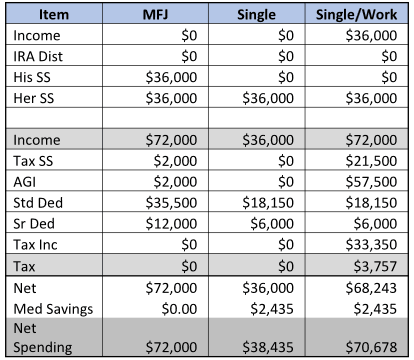 After accounting for the reduction in Medicare related spending, she has similar spending power. But she had to go back to work to achieve that. This, and the previous examples, reinforce the importance of understanding a couple’s financial details before and after the passing of a spouse. Income will likely be reduced, but expenses may also be reduced. Lower income retirees who depend primarily on both partners SS benefits may see the biggest impact. I also ran a comparison of our tax return for 2026, for both MFJ and if my wife filed single. I assumed our income consisted of my pension, my wife’s SS benefit, and my SS benefit had I claimed it on January 1, 2026. When I die my wife will receive 75% of my pension, and my higher SS benefit. The results were not surprising.
 Richard Connor is a semi-retired aerospace engineer with a keen interest in finance. He enjoys a wide variety of other interests, including chasing grandkids, space, sports, travel, winemaking and reading. Follow Rick on Twitter @RConnor609 and check out his earlier articles.
 Adam M. Grossman is the founder of Mayport, a fixed-fee wealth management firm. Sign up for Adam's Daily Ideas email, follow him on X @AdamMGrossman and check out his earlier articles.
From HumbleDollar Founder Jonathan Clements
NO. 3: WE SHOULD focus relentlessly on what we want from our financial life. That’ll motivate us to save, drive our investment strategy—and help ensure we pursue the goals we care about most.
ILLUSION OF CONTROL. If we shake the dice vigorously, we feel we’re more likely to get the roll we want. Similarly, if we follow the stock market closely and trade often, we feel more control over our returns. But in truth, this can hurt results, as we act impulsively and rack up costs. A better strategy: Focus on things we can control, like risk, taxes and expenses.
SEARCH FOR UNCLAIMED property. Every state has a program for returning lost and forgotten assets to their rightful owners. Those assets include stocks, uncashed dividends, bank accounts, traveler’s checks, the contents of safe deposit boxes and utility company security deposits. You can find further details and links to state websites at Unclaimed.org.
NO. 93: PAYING down a mortgage is often the best bond we can buy. We earn a return equal to the mortgage’s interest rate, which will typically be above the yield on high-quality corporate and government bonds. True, if we pay down a mortgage, we’ll have less mortgage interest to deduct—but that deduction is now less valuable, thanks to 2017’s tax law.
NO. 3: WE SHOULD focus relentlessly on what we want from our financial life. That’ll motivate us to save, drive our investment strategy—and help ensure we pursue the goals we care about most.
I asked my friends AI, what percentage of pre-retirement income to retirees actually live on. Of course, most of the data is survey based. The answer was 66% on average.
A T. Rowe Price/NewRetirement survey found that, nearly three years into retirement, retirees report living on 66% of pre-retirement income on average—and 57% said they live as well or better than before.
A Goldman Sachs Asset Management survey showed retirees receive ~60% of pre-retirement wages on average,
I WAS SCROLLING through social media recently and saw somebody dismiss retirement accounts as “paper wealth.” The argument was familiar: Your money is locked away and you’re waiting for permission to access it.
There’s a grain of truth here. Retirement accounts do come with rules. But much of the discussion online ignores how flexible these accounts actually are. More important, it ignores the enormous tax advantages.
Most people today will likely live well beyond age 59½.
A RECENT post by achnk53 about the impact of a spouse’s death on the survivor’s taxes piqued my interest. The post referenced an interesting Kiplinger article about the “Widow’s Penalty”, or the negative tax implications on a surviving spouse after the death of a spouse. A surviving spouse can file Married Filing Jointly (MFJ) in the year of their spouse’s death. In the full year following the spouse’s death you must file Single.
THE CHOICE BETWEEN a traditional retirement account or a Roth is a frequent topic on HumbleDollar. The choice is generally framed as a choice between paying taxes up front (a Roth), or deferring taxes until withdrawal (traditional). I thought it would be interesting to evaluate a real-life example of how this choice might work out.
In December of 2016 my wife and I had an opportunity to each open a Roth IRA. My wife took a partial sabbatical that year,
I am incensed when I read nonsense posted on social media about social security – “Congress stole the SS funds and never paid it back,” “there would be plenty of money if we didn’t give it to people not eligible” and worse. All nonsense.
Is it worth me getting upset over? It is, because uninformed people believe it and now it appears people are acting on the lies and misinformation they read and hear. They don’t understand that SS can’t go bankrupt or run out of money and that there is a different between SS’s ongoing revenue and the reserve trust.
I recently explained some facts about Social Security spousal benefits and upon doing so discovered there were some questions related to the linkage of spousal and survivor benefits. I delved deeper into survivor benefits and found some interesting facts about them as well.
Survivor vs spousal benefits. Survivor benefits are separate from spousal benefits. While spousal benefits are capped at 50% of the workers full retirement amount (FRA), survivor benefits can pay up to 100 % of what the deceased was receiving or entitled to receive.

Health
My Name is Dan, and I’m a CPAP User
DAN SMITH | Sep 24, 2026
In Retirement
Widow’s Penalty Redux
ArticleRichard Connor | Sep 26, 2026
- Her total income would be 68% of our combined pre-death income.
- Her annual tax bill would be $1,250 more than our joint tax bill.
- Her effective tax rate would increase by 4.2%.
- 85% of her SS benefits would be taxable
- Her spendable income after taxes would be about 65% of the joint amount.
- She would lose about 20% of the new Senior Deduction
- She would have no NJ State Tax liability
I then ran an additional scenario with the same assumptions, but also assuming we were 4 years older and would both have to take initial RMDs in 2026. This scenario reflects one of the concerns frequently expressed when discussing this topic – what happens when the surviving spouse is responsible for reporting the income from both RMDs on her Single tax return. The results changed to reflect the scenario.- Her total income would be about 79% of our combined pre-death income.
- Her annual tax would be $708 more than the joint tax filing.
- Her effective tax rate would increase by 3.8%.
- Her spendable income after taxes would be about 80% of the joint amount.
- She would lose all of the new Senior Deduction.
- Her NJ State Income tax would be $540 more than the joint tax filing.
- She would be pushed up one IRMAA bracket in 2028.
These results are a simplified look at our finances today. My pension and my wife’s SS benefit cover our non-discretionary, and a decent portion of our discretionary, expenses. The wild card is travel – how much we spend in any year is our choice and may require additional income. I’m about 11 months from claiming my SS benefit, at which point virtually all of our expenses will be covered in a fairly tax-efficient way. RMDs are still 4 years away. This was a good exercise to get a feel of how my demise would impact my wife’s finances. It would have some financial impacts, but I believe our plan can handle them. I’m considering running some more detailed projections varying the age at death to assess the impacts, but a quick look made me reasonably confident our retirement savings will be adequate, even considering long term care. I will also continue to look at Roth conversions each year.In Retirement
Keep an eye on Medigap policies
R Quinn | Sep 26, 2026
Investing
Financial Lessons
ArticleAdam M. Grossman | Sep 26, 2026
From HumbleDollar Founder Jonathan Clements
Lists
Why HumbleDollar?
In Retirement
The Security Money Can’t Buy
Dennis Friedman | Sep 25, 2026
Retirement
Will Congress Wait Until the Last Minute on Social Security?
Jeff Peck | Sep 27, 2026
In Retirement
Is your retirement plan counting on a Social Security COLA in the future?
R Quinn | Sep 24, 2026
Behavior
The Art of Making Do
Mark Crothers | Sep 25, 2026
Spending
Little luxuries
greg_j_tomamichel | Sep 19, 2026
Spending
Anyone For S.K.I.ing?
Mark Crothers | Sep 22, 2026
Behavior
Time Is Priceless
Andrew Clements | Sep 23, 2026